Introduction and Overview
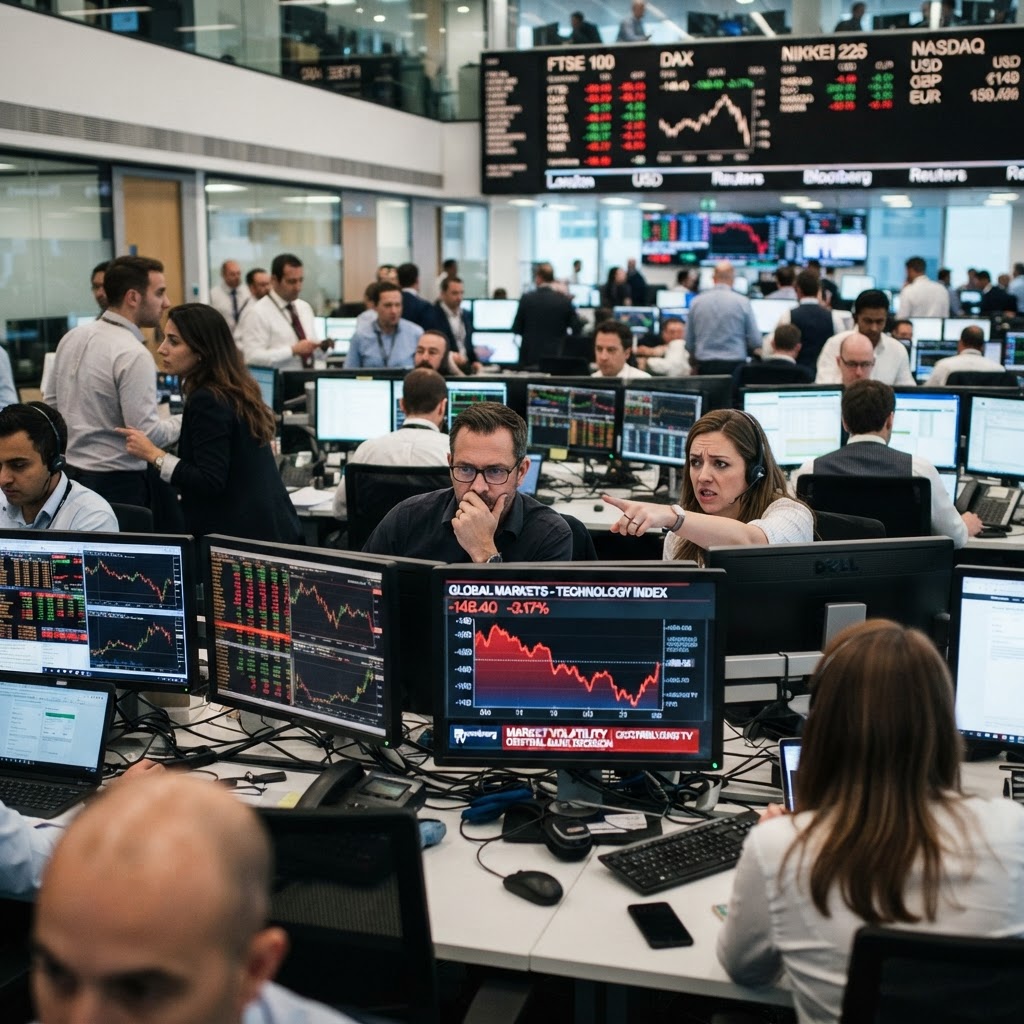
Financial markets across the globe were thrown into sharp recalibration following an unexpected monetary policy pivot announced by central banking authorities. The unexpected maneuver dismantled widely held consensus forecasts and forced institutional investors, algorithmic funds, and corporate treasuries to instantly reassess risk premiums, capital expenditure budgets, and portfolio durations. Within moments of the announcement, benchmark equity indices tumbled, government bond yields registered abrupt dislocations, and foreign exchange trading desks experienced severe liquidity compression.
The surprise policy shift highlighted growing concerns regarding persistent underlying inflation pressures and broader macroeconomic volatility. For months, forward guidance had conditioned the marketplace to anticipate an uninterrupted trajectory of monetary stability, fostering an environment where speculative tech valuations and leverage had rapidly expanded. By diverging sharply from established expectations, policymakers delivered an unmistakable warning shot, underscoring that their statutory mandate of price stability takes absolute precedence over asset valuation comfort.
As trading desks digested the immediate implications of the policy statement, the reverberations crossed regional borders and asset classes with remarkable speed. Cross-border capital flows shifted dynamically, with emerging market assets suffering abrupt liquidations as capital rotated back toward safe-haven sovereign paper and dollar-denominated reserves. Concurrently, corporate debt spreads widened significantly, forcing enterprise finance leaders to rethink immediate issuance schedules and debt-refinancing programs.
Advertisement

This decisive action illustrates the delicate tightrope modern monetary institutions must walk in an interconnected and technologically complex global economy. The ripple effects extend far beyond traditional financial trading hubs like New York, London, Tokyo, and Frankfurt. They penetrate domestic retail banking, everyday small business lines of credit, immigrant remittance channels, and international venture capital syndicates, signaling a transformative chapter in the post-pandemic macroeconomic cycle.
The shift also brought new scrutiny to the interaction between monetary mechanics and the rapidly expanding digital economy. Because advanced software infrastructure, artificial intelligence development, and cloud platform buildouts require immense upfront capital commitments, any abrupt adjustment to the cost of capital disproportionately alters tech sector valuations and enterprise investment timetables. As a consequence, boardrooms worldwide are actively restructuring operational budgets to prepare for prolonged capital discipline.
Market participants are now coming to terms with the reality that the structural parameters governing global liquidity have fundamentally transformed. The assumption that central banks would invariably step in with liquidity injections or immediate rate relief at the earliest sign of financial turbulence has been decisively shattered. As sovereign balance sheets retrench and interest rate regimes anchor at higher plateaus, the entire global financial architecture is entering an era defined by rigorous underwriting, elevated hurdles, and heightened sensitivity to external shocks.
Background and Context
To comprehend the sheer magnitude of the recent policy announcement, one must examine the unusual macroeconomic backdrop that has unfolded over the past decade. Following the structural supply chain shocks of the early 2020s and the subsequent aggressive tightening cycle enacted to rein in multi-decade high inflation, global central banks spent years attempting to orchestrate an orderly economic normalization. For an extended period, monetary authorities leaned heavily into transparent forward guidance, carefully telegraphing every basis-point adjustment to prevent disorderly bond market sell-offs.
This prolonged era of predictive communication, however, gradually induced a sense of institutional complacency across capital markets. Trading algorithms and quantitative strategies increasingly operated under the assumption that central banks would invariably step in or temper their stance whenever financial conditions tightened excessively. Highly speculative technology sectors, private credit vehicles, and high-growth venture ecosystems expanded aggressively under this presumption, relying heavily on cheap liquidity and stable discount rates to justify unprecedented enterprise multiples.
Beneath the surface of surface-level stability, systemic pressures continued to accumulate across structural economic layers. While headline inflation indices exhibited modest decelerations as supply bottlenecks normalized, core inflation metrics—particularly across labor-intensive service industries, tech engineering talent pools, and urban housing—remained stubbornly sticky above central bank targets. Consumer resilience, supported by structural changes in employment and sustained public infrastructure investments, consistently prevented the disinflationary cooling that policymakers had anticipated.
Furthermore, structural shifts within the digital and energy sectors fundamentally altered the underlying cost structure of global production. The exponential buildout of artificial intelligence compute centers, massive semiconductor manufacturing facilities, and green grid transitions generated unprecedented demand for energy, raw materials, and specialized technical expertise. These capital-intensive megatrends introduced durable supply constraints that traditional monetary easing could neither resolve nor ignore.
As early economic signals started warning of reaccelerating wage trends and sticky input costs, central banks found themselves trapped between conflicting imperatives. Maintaining artificially accommodative financial conditions risked anchoring long-term inflation expectations well above the standard two percent objective, whereas aggressive tightening threatened to trigger sovereign debt stress and sudden corporate insolvency. The policy framework had arrived at an unsustainable juncture, making an eventual, decisive break with previous forward guidance virtually inevitable.
Historical precedents from past monetary tightening cycles demonstrated that prolonged periods of opaque forward guidance often end in severe volatility when economic realities force an abrupt divergence. The classic framework established during the late twentieth century relied on discretion rather than rigid public signaling, allowing policymakers room to maneuver when structural shifts disrupted theoretical economic modeling. Today's authorities have rediscovered that excessive communication can paralyze policy independence, turning public statements into self-fulfilling market constraints rather than informative macroeconomic tools.
Key Developments
The turning point arrived during the unscheduled policy release, wherein the central bank broke definitively with its prior forward guidance by enacting an abrupt policy modification accompanied by aggressively hawkish operational revisions. Rather than maintaining the expected steady-state path, the committee announced immediate adjustments to benchmark borrowing benchmarks alongside an accelerated pace of quantitative balance sheet reductions. The surprise decision struck markets with immediate force, catching leveraged institutional funds completely flat-footed.
Within the first hour of trading following the release, major equity benchmarks witnessed sudden intraday reversals of over three percent, led principally by large-cap cloud software, semiconductor fabrication, and clean-tech equities. Concurrently, yields on benchmark two-year and ten-year sovereign debt obligations surged by historic single-session margins, producing an inverted yield curve dynamic that intensified anxieties regarding a potential mid-term economic contraction. Foreign exchange desks experienced explosive order flows as institutional traders scrambled to cover short positions.
Central to the market turmoil was the complete overhaul of the bank's forward guidance language, which had previously assured market participants that current policy settings were restrictive enough to naturally guide inflation back to target. In the official communique, policymakers explicitly retracted that reassurance, citing structural labor mismatches, persistent energy market volatility, and an unyielding services component in recent inflation data prints. The removal of this protective rhetoric forced traders to price out projected rate cuts entirely, replacing them with anticipations of extended tightness.
The policy announcement also targeted the ongoing expansion of speculative credit markets by imposing tighter capital reserve guidelines on non-bank financial intermediaries and institutional lenders. By signaling an aggressive posture toward private credit valuations and speculative asset syndications, the bank targeted the excessive liquidity that had quietly accumulated in alternative finance channels over recent quarters. This targeted regulatory signal magnified the market's defensive response.
The key developments that immediately defined the subsequent trading sessions include:
- A synchronized spike in benchmark short-term sovereign bond yields across the United States, Europe, and Asia, triggering widespread liquidations of duration-sensitive fixed-income portfolios.
- A dramatic surge in the trade-weighted value of safe-haven reserve currencies, creating sudden exchange-rate volatility for emerging market central banks attempting to stabilize domestic currencies.
- A severe repricing of high-growth technology equities, software valuation multiples, and early-stage venture capital syndication rounds.
- A rapid widening of sovereign and corporate credit default swap spreads, reflecting rising counterparty risk and heightened anxiety surrounding upcoming corporate debt refinancing walls.
- A sharp tightening in commercial real estate underwriting standards as regional and international lenders revised their internal stress-test models to match higher terminal policy rates.
Institutional trading desks were forced to rapidly dismantle long-duration carry trades, triggering sudden secondary dislocations across global commodity derivatives. As margin requirements increased across international clearinghouses, multi-strategy hedge funds liquidated profitable positions in energy and industrial metals to meet capital calls on duration-exposed assets. This cross-market deleveraging underscored the speed with which modern quantitative trading systems transmit shocks across previously uncorrelated asset classes.
Expert Analysis and Perspectives
Market analysts, academic economists, and industry leaders were immediate in their appraisal of the central bank's unexpected move, offering competing interpretations of its wisdom and long-term implications. While orthodox inflation hawks applauded the institution's commitment to eradicating structural price pressures, market liquidity analysts warned that the sudden communication breakdown could damage central bank credibility and unnecessarily shock the real economy.
Dr. Marcus Vance, Chief Global Strategist at Vanguard Macro Insights, highlighted the urgent strategic calculations governing the committee's controversial maneuver:
The central bank realized that patience was rapidly turning into complacency across global boardrooms. By delivering an unambiguous shock rather than a series of timid incremental adjustments, policymakers intentionally disrupted the speculative inertia that was quietly refueling wage-price spirals and overleveraged tech asset valuations.
Other veteran financial economists voiced serious concern regarding the bluntness of the policy transmission mechanism. Critics pointed out that while traditional monetary tools are exceptionally effective at cooling consumer credit demand, they are inherently incapable of resolving supply-side bottlenecks, such as specialized semiconductor shortages, electric grid constraints, or geopolitical trade barriers. In this view, using blunt interest rate tools to address structural issues risks crushing genuine productive capacity alongside speculative excess.
Elena Rostova, Managing Director of International Capital Markets at Horizon Advisory Group, emphasized the difficult terrain facing emerging market jurisdictions in the wake of the policy shift:
When the world's preeminent central bank executes an abrupt pivot of this scale, emerging markets inevitably absorb the greatest collateral damage. Developing economies are suddenly forced into defensive monetary tightening simply to protect their currencies from rapid depreciation, even when their domestic underlying economies urgently require counter-cyclical monetary support.
From the technology industry perspective, executives and venture capitalists have expressed acute frustration with the regulatory volatility. Tech leaders argue that modern innovation cycles—specifically multi-billion-dollar sovereign artificial intelligence models, quantum compute research, and advanced robotics—demand steady, predictable discount rates spanning decades. Sudden oscillations in monetary direction risk freezing vital digital transformation initiatives across enterprise software ecosystems.
Julian Thorne, Senior Partner at Apex Global Ventures, framed the corporate fallout succinctly:
For more than a decade, software architecture and digital enterprise scale were built upon a foundation of practically frictionless capital access. That era has definitively terminated, and technology founders must immediately pivot from growth-at-all-costs models to cash-flow discipline, unit economics, and operational austerity.
Quantitative strategists also highlighted the mechanical effects of changing discount rates on long-duration equities. When interest rates rise unexpectedly, the present value of earnings projected ten or fifteen years into the future decreases substantially. This mathematical reality disproportionately impacts technology enterprises whose current valuations are heavily weighted toward distant potential revenue rather than immediate operating profitability.
Impact and Implications
The sudden monetary realignment carries far-reaching consequences that reverberate through every layer of the global financial system and real economy. At the corporate level, enterprise treasurers who had postponed refinancing lower-yielding debt maturities are now confronted with a punitive refinancing landscape. The cost of rolling over maturing commercial paper and syndicated loans has multiplied, draining capital reserves that would otherwise be directed toward hiring, research, and geographic expansion.
The technology sector faces a uniquely severe reckoning following years of debt-fueled development. Large cloud service providers and enterprise software firms are reevaluating their multi-billion-dollar commitments to data center construction, semiconductor procurement, and artificial intelligence hardware deployment. As borrowing costs escalate, projects that once met internal return-on-investment hurdles under low discount rates are suddenly being mothballed or delayed indefinitely.
Beyond enterprise boardrooms, the monetary pivot directly affects household balance sheets across multiple continents. Mortgages, automotive loans, and revolving credit facilities have recalibrated upward with immediate effect, compressing discretionary consumer spending. This reduction in disposable income threatens consumer-facing tech platforms, subscription streaming models, and digital commerce marketplaces that depend entirely on robust retail consumption to sustain top-line growth.
The broader structural implications extend deep into international banking balance sheets and sovereign debt management. Key operational disruptions currently unfolding include:
- A structural cooling in venture capital deployment, resulting in delayed initial public offerings, down-rounds for growth-stage technology startups, and corporate consolidation.
- An accelerated widening of yield spreads between sovereign debt issued by core reserve economies and emerging market sovereign paper, curtailing external funding access for developing nations.
- A renewed focus on cash flow positive enterprises over visionary growth narratives, shifting capital allocations toward defensive value sectors, traditional energy, and physical infrastructure.
- Increased strain on sovereign treasuries burdened with ballooning debt service obligations, constraining public budgets for industrial policy, social programs, and digital modernization initiatives.
- A persistent revaluation of commercial real estate debt securities, prompting institutional asset managers to write down the net asset values of private real estate equity portfolios.
The impact on cross-border commercial trade is equally profound. As international borrowing costs spike, the cost of trade credit insurance and letters of credit rises correspondingly, discouraging medium-sized exporters from engaging in complex transcontinental supply agreements. This dynamic threatens to accelerate global economic fragmentation, driving regional supply chain reshoring at the expense of international economic efficiency.
Reactions from the Diaspora Community
The macroeconomic ramifications of the central bank's unexpected pivot have generated immediate and profound ripples throughout international diaspora communities. For millions of immigrant professionals, expatriate workers, and cross-border families, shifts in major currency valuations and central bank interest rates represent far more than abstract financial metrics. They directly dictate household purchasing power, remittance affordability, and the long-term viability of cross-border investments.
As the value of safe-haven reserve currencies surged following the announcement, diaspora workers sending funds back to family members in developing nations experienced a complex double-edged sword. While the stronger currency temporarily bolstered the purchasing power of converted payments in local terms, the severe inflation and currency depreciation in recipient countries rapidly eroded those immediate gains. Daily essentials, imported fuel, and medical supplies in home countries saw instant price escalations, forcing senders to increase overall remittance volumes to provide the same real standard of living.
Diaspora entrepreneurs and small business operators who maintain commercial ties between their adopted homelands and countries of origin have reported widespread operational gridlock. Cross-border trade credit lines have tightened abruptly, and foreign exchange hedging instruments have become cost-prohibitive for small enterprises. Many diaspora-owned trading houses, which import agricultural commodities, textiles, and specialty goods, find themselves struggling to settle invoices due to rapid swings in wholesale exchange rates.