Market Update: Record Highs Explained
Breaking down the factors behind the stock market's record performance.
Markets Rally as Inflation Cools
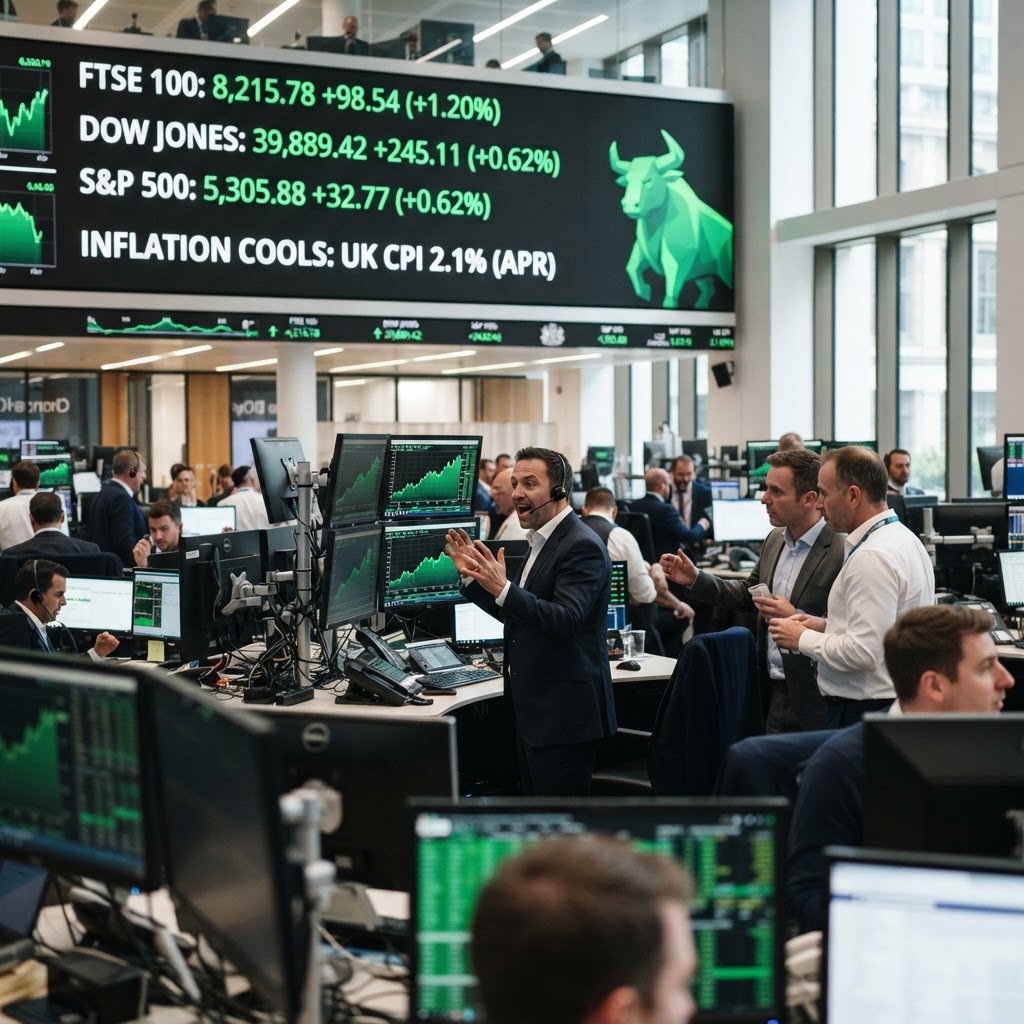
Global equity exchanges and credit markets experienced a broad-based surge across major trading desks this week as freshly published government inflation figures confirmed that consumer and wholesale price pressures are moderating faster than anticipated. On Wall Street, European bourses, and across emerging market trading centers, investors greeted the decelerating data with aggressive buying activity, propelling benchmark equity indexes toward historic highs and driving down government bond yields. The relief sweeping through trading floors reflects a growing conviction that major monetary authorities, led by the Federal Reserve and the European Central Bank, have managed to steer their respective economies through an aggressive monetary tightening cycle without triggering the deep contraction many feared.
The benchmark S&P 500 index climbed sharply to notch fresh record valuations, supported by parallel advances in the technology-heavy Nasdaq Composite and the industrial-heavy Dow Jones Industrial Average. Meanwhile, European shares on the STOXX 600 advanced steadily, and Asian equities posted sizable sessions of gains as cross-border portfolio managers rebalanced away from cash holdings into long-duration growth assets and cyclical industry leaders. Treasury yields slipped notably at the front end of the curve, illustrating that fixed-income traders are pricing in a substantially clearer runway for baseline interest-rate cuts through the remaining fiscal quarters. Market participants who had spent months positioned defensively quickly found themselves compelled to chase risk assets as volatility metrics retreated across the board.
Yet beneath the euphoria rippling across dealing rooms lies a nuanced landscape defined by distinct macroeconomic challenges and structural shifts. While falling headline figures suggest that post-pandemic supply constraints and commodity spikes have dissipated, core consumer components such as shelter, healthcare, and services have demonstrated considerable stickiness. Market observers and corporate leadership teams are closely scrutinizing whether the decelerating price indicators stem purely from a normalization of global supply chains or if they also point toward a gradual softening of aggregate consumer demand. Consequently, while the equity market's immediate reaction has been celebratory, structural economists caution that the journey back toward official two-percent targets demands sustained vigilance.
Advertisement

For global business executives, portfolio custodians, and diaspora households navigating transnational commerce, this market inflection point carries immense practical relevance. Borrowing costs, international capital allocations, mortgage commitments, and foreign remittance dynamics are all directly calibrated to the policy trajectories set during these crucial market windows. As global borrowing costs prepare to adjust, the transition away from peak interest rates promises to reshape corporate balance sheets and multinational investment flows in profound ways. Understanding the operational mechanisms driving this market rally requires examining both the immediate statistical prints and the broader macro-financial framework that has dictated economic policy over the past four years.
Background and Context
The macroeconomic forces setting the stage for the current rally represent the culmination of an unprecedented chapter in modern monetary history. In the immediate aftermath of the 2020 global pandemic, central banks worldwide lowered benchmark lending rates to near-zero bounds and embarked on extraordinary quantitative easing programs to avert catastrophic liquidity freezes and stave off economic depression. Concurrently, national governments unleashed trillions of dollars in fiscal stimulus packages designed to insulate households and private enterprises from quarantine measures and supply disruption. While these coordinated interventions successfully underwrote a rapid global recovery, they inadvertently planted the seeds of an aggressive inflationary cycle once commercial activity rebounded sharply against compromised global supply logistics.
By late 2021 and early 2022, compounding supply chain bottlenecks, labor misallocations, and an abrupt escalation in geopolitical friction—punctuated by severe disruptions in Eastern European grain and energy supplies—catapulted global inflation to multi-decade peaks. Consumer price indexes in major industrialized economies breached nine percent, an inflationary velocity unseen since the late 1970s and early 1980s. Faced with the risk of unanchored public inflation expectations, the Federal Reserve, the Bank of England, the European Central Bank, and the Bank of Canada reversed course with historic speed. Central bankers embarked on the most aggressive credit tightening cycle in over forty years, orchestrating consecutive supersized rate hikes that lifted borrowing benchmarks from baseline zero to well above five percent within an exceptionally compressed timeframe.
This abrupt tightening regime triggered intense dislocations throughout 2022 and 2023, causing painful contractions in sovereign bond valuations and punishing high-multiple technology equities that had flourished during the low-rate era. Regional banking systems faced severe balance sheet stresses as rising yields compromised held-to-maturity bond portfolios, while the residential mortgage sector ground to near stagnation as commercial financing rates reached multi-decade records. Market forecasters and leading academic economists routinely projected an inevitable global recession, warning that crushing inflation would demand a severe contraction in labor markets and heavy corporate bankruptcies before price stability could be restored.
Against these dire predictions, the resilience of corporate balance sheets and resilient labor dynamics began to carve out an alternative path commonly termed a soft landing. Supply bottlenecks unwound organically as container shipping lanes cleared, energy producers expanded output, and manufacturing lines adjusted to post-pandemic consumer patterns. Corporate profit margins contracted back toward historical norms without triggering widespread workforce liquidations, while productivity gains insulated domestic output. By early 2024, disinflationary trends gathered momentum across North America and Europe, prompting central bankers to pause rate increases and signaling to global investors that the terminal policy rate had finally been attained.
Key Developments
The catalyst for the current equity surge came in the form of successive, softer-than-expected inflation metrics published by official statistical bureaus, confirming that aggregate price growth has moderated significantly. The consumer price index prints revealed that annual headline inflation has settled back down toward the two-percent threshold, marked by sharp decelerations in durable goods prices, vehicle sales, apparel, and consumer electronics. Crucially, wholesale prices and producer index readings remained flat or moved into fractional territory, proving that input costs for industrial manufacturers and primary producers are no longer exerting upward pressure on wholesale distribution channels.
Energy markets have served as a vital stabilizing mechanism in this disinflationary equation. Crude oil benchmarks receded sharply from their earlier seasonal peaks, reflecting robust non-OPEC oil production, particularly from the Western Hemisphere, coupled with tempered industrial demand in key Asian manufacturing hubs. The decline in wholesale gasoline, diesel, and natural gas costs has rippled directly through domestic supply chains, providing relief to logistics carriers, freight haulers, and utility grids. This easing of commercial overhead has permitted retail organizations and food processors to stabilize grocery shelves and wholesale distribution rates without sacrificing operating viability.
Financial assets responded immediately across global desks, with capital rotating decisively out of short-term cash reserves and high-yielding money market vehicles into broader equity baskets. Technology leaders and semiconductor manufacturers led the initial advance, before the rally widened to embrace small-cap equities, regional lenders, real estate investment trusts, and heavy industrial exporters that had languished under elevated borrowing rates. Concurrently, sovereign yields across the United States, the United Kingdom, and the eurozone posted steep downward revisions, with benchmark two-year Treasury yields sliding to price in successive monetary cuts across upcoming central bank gatherings.
To summarize the core statistical markers and tangible market reactions observed during this inflection week, the following developments highlight the breadth of the current economic environment:
- Consumer price index growth declined to its lowest localized levels in three years, settling into a comfortable sub-three percent annualized band led by substantial contractions in consumer staples, retail apparel, and durable manufactured goods.
- Wholesale input benchmarks, as captured by the Producer Price Index, registered unchanged or fractionally lower month-over-month prints, effectively extinguishing supply-chain wholesale pressure on downstream commercial vendors.
- Benchmark sovereign debt yields dropped considerably, with two-year yields tumbling as futures contracts rapidly upgraded probabilities for a series of 25-to-50 basis point benchmark rate cuts by major central banking institutions.
- Global equity indices expanded beyond the narrow technology megacap leadership of early 2024, exhibiting healthy participation from mid-cap industrials, infrastructure builders, retail distributors, and residential developers.
- Foreign exchange benchmarks experienced a broad recalibration, as the United States Dollar Index retreated slightly against the Euro, British Pound, and prominent emerging market currencies, reflecting altered interest-rate differentials.
Expert Analysis and Perspectives
Senior market analysts and prominent macro-economists view this latest market surge as validation that central banking authorities have achieved what many deemed mathematically impossible: substantial disinflation without widespread structural unemployment. Economists emphasize that while past disinflationary episodes required severe industrial contraction, the post-pandemic supply restoration allowed pricing metrics to self-correct as capacity normalized. The ongoing debate on trading desks has now shifted entirely away from whether central banks will raise interest rates toward the appropriate pace and magnitude of future rate reductions necessary to avoid overtightening policy.
Douglas Porter, Chief Economist at BMO, underscored the historic significance of this economic transition when evaluating the global picture, highlighting how exceptional the current environment is compared to historical tightening cycles:
Some of the best news that we’ve seen is that, here in Canada and globally as well, inflation has really relented to the point where many central banks are actually comfortable with bringing down interest rates, and we got there without a full-blown recession.
Echoing these sentiments, portfolio strategists emphasize that falling interest rates fundamentally alter the structural valuation metrics used to assess risk-bearing assets. Because higher discount rates disproportionately punish long-duration assets whose expected free cash flows sit well into the future, cooling inflationary pressures serve as a substantial tailwind for growth-oriented sectors, enterprise software vendors, and clean energy developers. By reducing the opportunity cost of holding equities relative to high-yielding treasury bills, financial institutions are systematically repositioning private client capital back into diversified equity allocations.
Ivana Delevska, founder of Spear Invest, articulated this core valuation mechanism when discussing how growth sectors respond to monetary shifts:
Inflation is not necessarily negative for technology. It's more about what inflation implies for the direction of interest rates. All tech sub-sectors will benefit from lower interest rates. A roughly 50 basis point move in interest rates is about a 10% impact for stocks.
Nevertheless, a prominent faction of fixed-income managers and research analysts urges institutional discipline, warning that market participants may be premature in assuming the inflation battle is permanently settled. These analysts argue that while commodity prices have softened, underlying wage settlements, service contracts, and structural housing shortages could produce stubborn baseline stickiness. They also observe that sovereign bond markets have produced an uncomfortably divergent profile, wherein short-term notes have adjusted aggressively to rate-cut speculation while long-duration bonds remain attentive to massive sovereign deficit issuance, domestic political transitions, and unpredictable geopolitical risks.
Michael Turrin, senior equity analyst at Wells Fargo, highlighted the delicate balance between structural valuation expansion and long-term earnings realities across corporate balance sheets:
Cooling inflation suggests less need to raise rates, which have an inverse relationship with tech valuations given the long duration. Most tech companies are still in growth mode, hence investors are valuing free cash flow well into the future.
Impact and Implications
The broader implications of cooling inflation and declining capital costs extend far beyond Wall Street equity desks, exerting direct influence over real-world industries, municipal governance, and consumer purchasing capacity. In the corporate sector, lower interest rates provide immediate relief to mid-market enterprises and capital-intensive industries that rely on revolving credit facilities and floating-rate commercial paper to maintain liquidity. Over the past twenty-four months, elevated borrowing expenses severely constrained corporate mergers, capital expansion projects, and industrial automation upgrades. As financing rates recede, corporate treasurers are initiating plans to refinance existing short-term obligations into favorable longer maturities, preserving operating margins and freeing capital for business hiring and strategic research.
The commercial and residential real estate landscapes are similarly positioned for a substantial reawakening. Skyrocketing mortgage rates effectively paralyzed residential home sales globally, trapping prospective homebuyers in unaffordable rental markets and leaving property owners unwilling to relinquish favorable historical financing terms. A structural reduction in baseline yields is beginning to compress mortgage borrowing rates, reviving mortgage origination activity and encouraging residential homebuilders to ramp up new housing starts. Concurrently, commercial property developers who faced refinancing cliffs on urban office complexes and logistics facilities now have a path toward stable recapitalizations, reducing systemic risk across regional commercial lending banks.
For consumer households, disinflation translates into a long-overdue restoration of real purchasing power. During the height of the inflationary surge, consumer wages failed to keep pace with soaring grocery, utility, and fuel bills, compelling families to draw down pandemic-era savings reserves and take on record levels of revolving credit card debt. With wage growth now modestly exceeding baseline consumer inflation prints, household disposable income is beginning to expand once again. This dynamic provides vital support to retail discretionary spending, leisure travel, and personal savings, sustaining economic stability without re-igniting demand-driven inflationary pressures.
The transition toward normalized capital conditions also carries specific structural consequences across several foundational sectors of the global marketplace:
- Capital goods and heavy manufacturing are experiencing renewed order backlogs as industrial clients gain the financing visibility required to commission large-scale factory installations and automated production facilities.
- Renewable energy and cleantech developments, which were severely challenged by capital expense increases and high discount rates, are seeing project pipelines revived across North America, Europe, and developing nations.
- Commercial logistics and global maritime shipping are stabilizing their operational tariffs as fuel expenses moderate and container freight volume returns to predictable, non-emergency routing patterns.
- Small and medium-sized enterprise credit facilities are loosening terms, allowing local service operations and regional retail proprietors to service debt without compromising frontline staffing.
- Sovereign debt markets are finding a sustainable pricing equilibrium, relieving national treasuries from the escalating debt-service burdens that have threatened public budgets and infrastructure investments over recent fiscal cycles.
Reactions from the Diaspora Community
For diaspora populations around the world, the cooling of global inflation and the subsequent market response carry distinct financial, familial, and operational implications. Transnational families who maintain economic linkages between host countries in North America, Western Europe, and their homelands across the Global South have lived on the frontline of currency volatility and price shocks. In recent years, diaspora workers found their hard-earned earnings severely pinched by rising domestic living costs in Western metropolitan areas, which simultaneously diminished their capacity to provide financial assistance to overseas relatives contending with severe local currency devaluations.
The moderation of domestic inflation in major developed economies provides meaningful relief for immigrant households, restoring their ability to send substantial cross-border remittances. As living costs normalize in urban diaspora hubs like London, Toronto, New York, and Paris, family heads are finding increased headroom in their monthly budgets to fund tuition, medical necessities, and construction projects back home. Moreover, the softening of the United States dollar and major Western currencies relative to emerging market instruments has lowered foreign exchange conversion volatility, making remittance transfers significantly more predictable and cost-effective for everyday diaspora senders.
Beyond basic familial remittances, the market rally is altering the direct investment strategies of wealthy diaspora professionals, immigrant entrepreneurs, and diaspora-backed venture networks. During the period of ultra-high interest rates, many diaspora investors opted to park capital in domestic Western treasury notes and insured term deposits, which provided risk-free yields above five percent without the political or exchange-rate risks of international investment. With global yields pulling back and equity markets exhibiting resilient momentum, capital allocators are aggressively rotating funding back into cross-border diaspora investments, financing real estate developments, small-business expansions, and technology startups across Sub-Saharan Africa, Latin America, South Asia, and the Caribbean.
Was this article helpful?
Support Jennifer Adams
Enjoyed this article? Send a tip to show your appreciation.
React to this story
Get our top stories in your inbox
Join thousands of readers — daily updates, no spam.
Comments
Comments (0)
Be the first to comment.