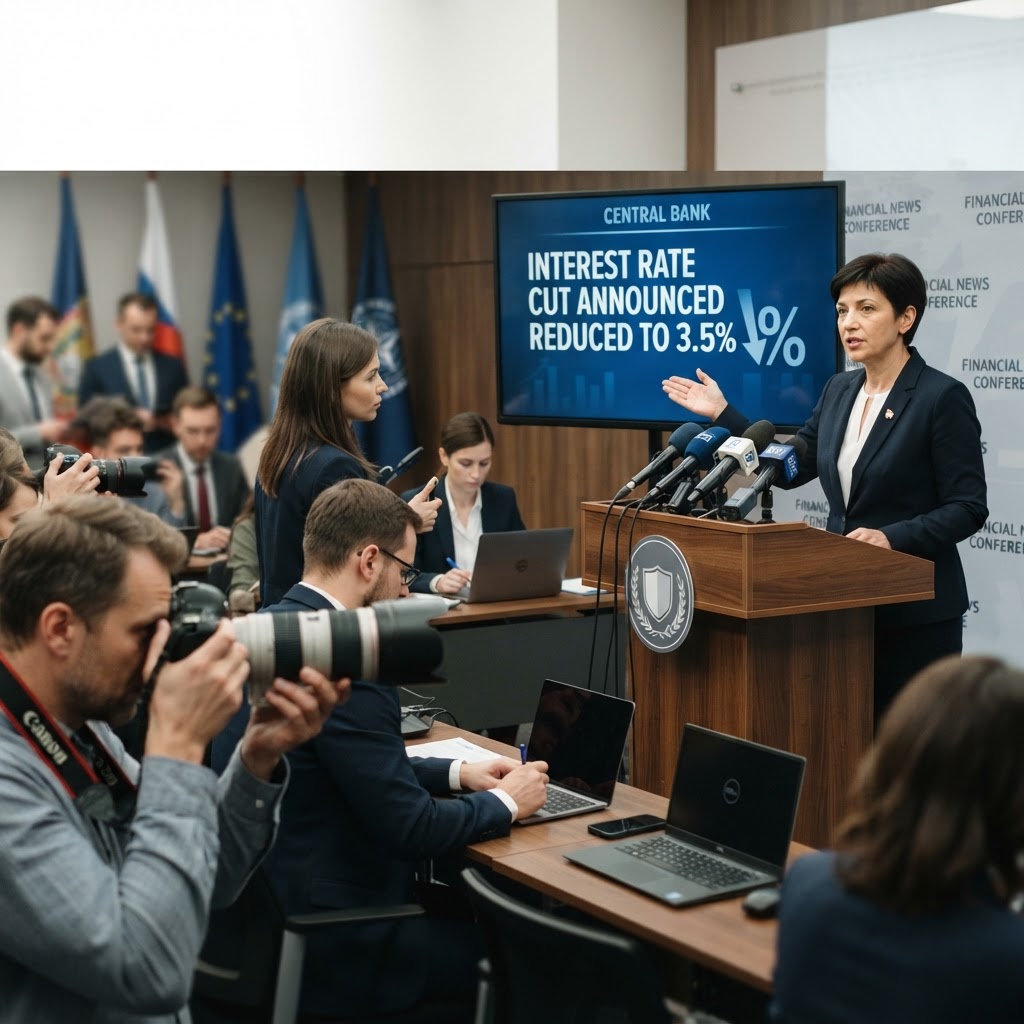
In a decisive move aimed at revitalizing domestic economic momentum, the Central Bank announced a benchmark interest rate cut following an intensive, two-day meeting of its monetary policy committee. The decision, which marks a pivotal shift in the institution's macroeconomic stance, lowers the policy rate by 25 basis points, bringing immediate relief to borrowing costs across consumer and corporate credit sectors. The adjustment arrives after months of contentious internal debate and intensifying speculation within global financial markets.
The reduction reflects the central bank’s growing confidence that inflationary pressures, which had reached multi-decade highs over the preceding two fiscal years, have fundamentally subsided and are on a sustainable trajectory toward the long-term target of 2.0 percent. According to the committee's policy statement, core consumer price indicators have shown a sustained deceleration over three consecutive quarters, providing policymakers the necessary latitude to shift attention from curbing demand to safeguarding employment and preserving baseline economic growth.
Policymakers voted in favor of the reduction by a decisive majority, though dissenting votes underscored lingering anxieties regarding volatile energy markets and stubborn wage pressures in service-oriented industries. The committee acknowledged these risks in its formal summary, emphasizing that while the restrictive monetary posture had successfully cooled aggregate demand, maintaining excessively high rates posed an imminent threat to fixed business investment, residential construction, and labor retention.
Advertisement

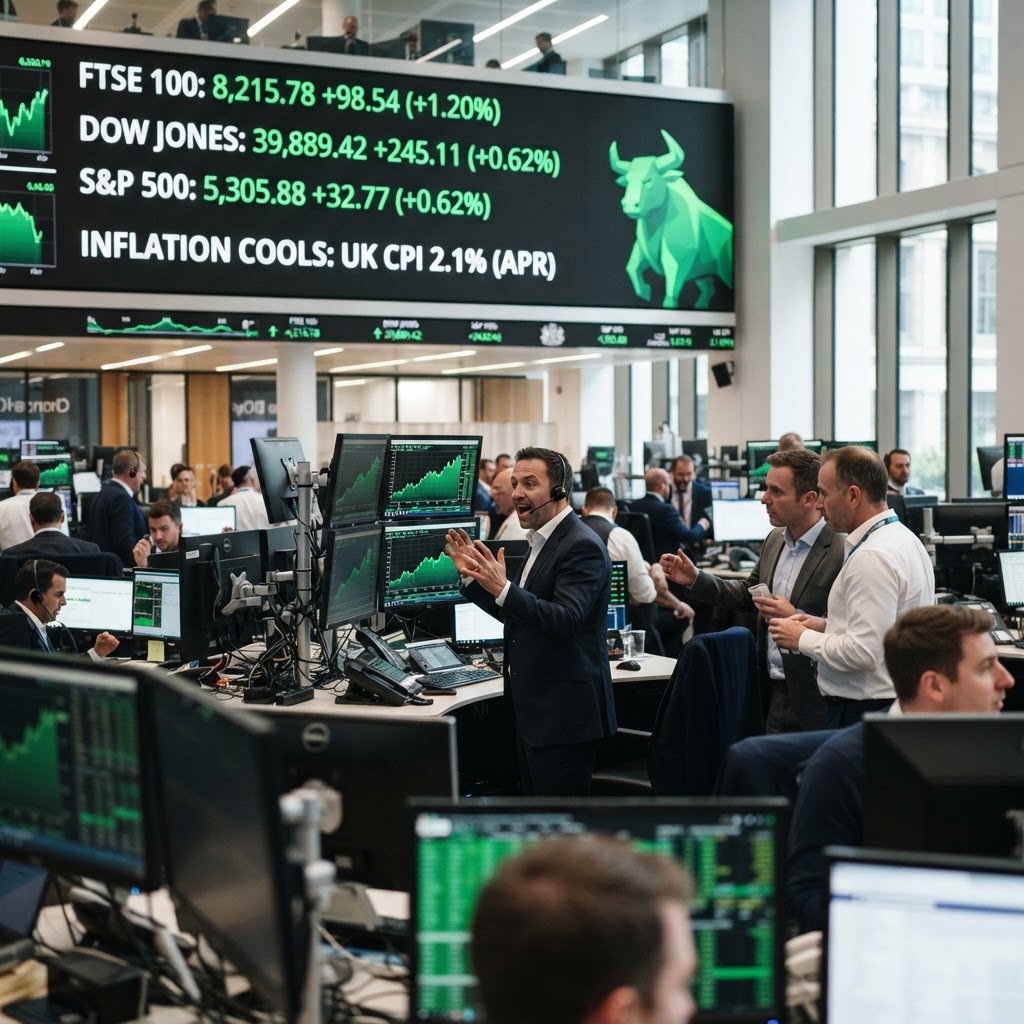
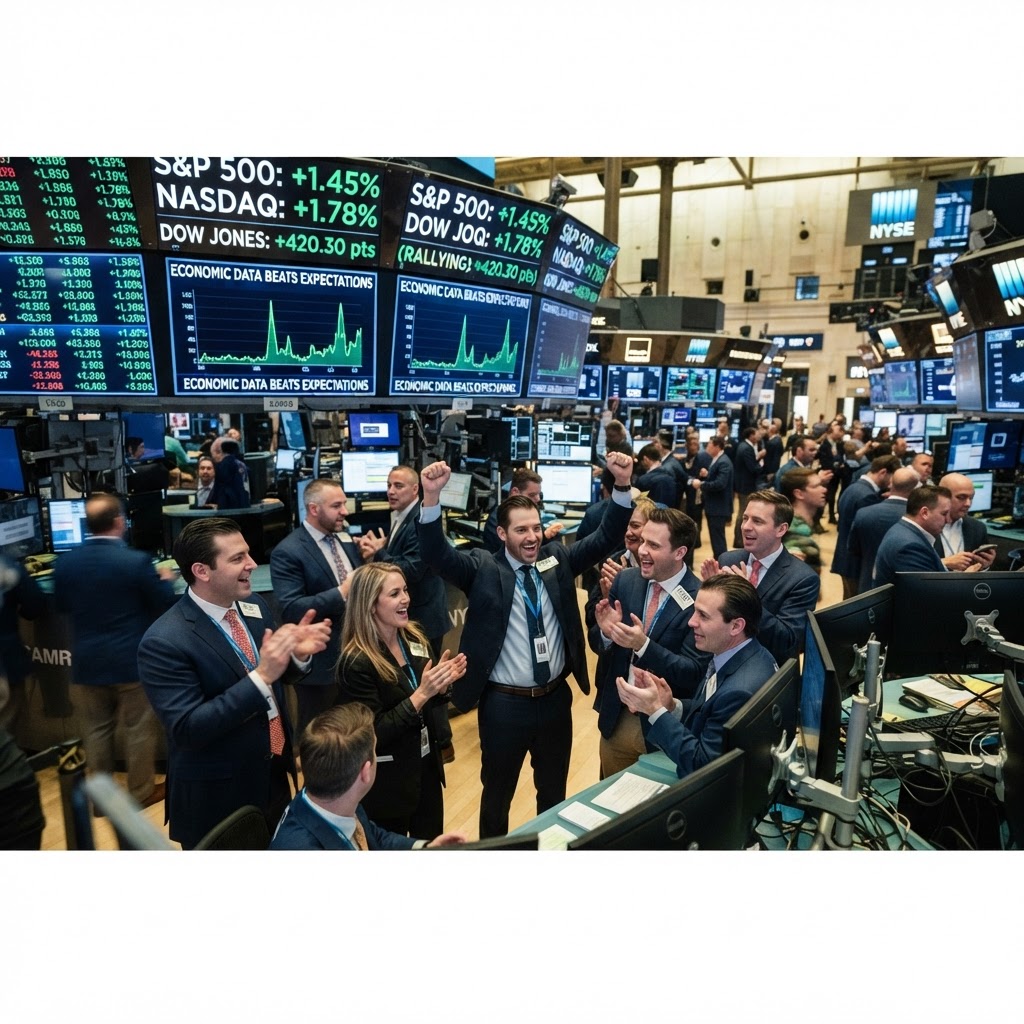
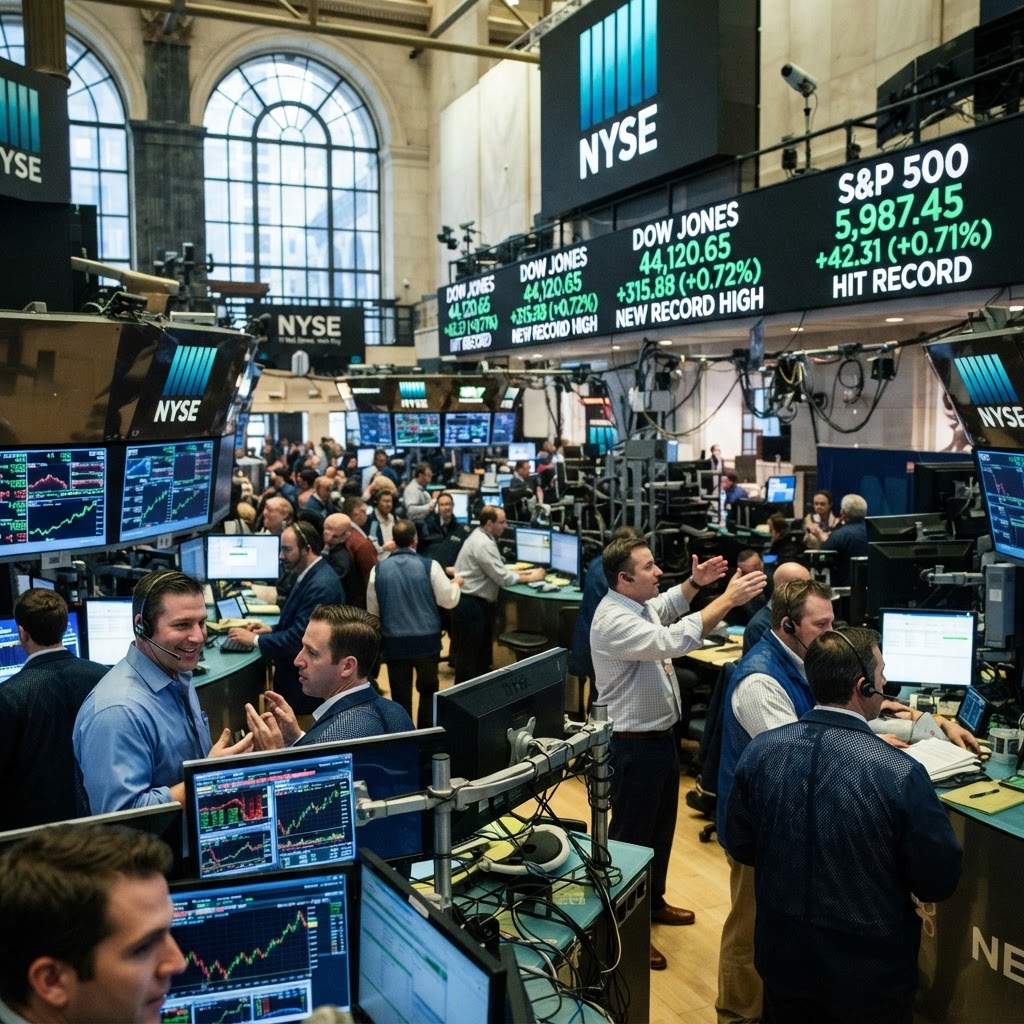
The response across international and domestic financial exchanges was immediate and pronounced. Benchmark equity indices rallied within minutes of the official statement’s publication, led by strong gains in rate-sensitive segments such as real estate, utilities, and high-growth technology firms. Conversely, sovereign bond yields fell steeply across short- and medium-term maturities as debt traders adjusted their terminal rate expectations downward. The domestic currency experienced modest downward pressure against major trading partners, a development anticipated by foreign exchange analysts as yield differentials narrow against other sovereign jurisdictions.
Commercial banking institutions reacted swiftly to the central bank's directive, with several leading retail lenders announcing downward adjustments to their prime lending rates scheduled to take effect at the start of the coming business week. For households carrying variable-rate liabilities, particularly adjustable mortgages and consumer credit facilities, the reduction offers a tangible reprieve from high debt-servicing burdens that have strained discretionary household budgets over recent months. Industry observers anticipate that reduced borrowing costs could reignite consumer appetite for big-ticket purchases, which had largely stalled amid the elevated rate environment.
Despite the optimistic market reception, macroeconomic analysts and corporate stakeholders remain divided over the broader implications of the easing cycle. Proponents of the move argue that the central bank acted with prudent timing, averting a potential policy-induced slowdown before structural cracks could widen across the labor market. Representatives from industrial manufacturing associations publicly welcomed the lower cost of capital, indicating that suppressed business investment may now rebound as firms dust off deferred expansion plans, capital expenditure projects, and infrastructure modernizations.
Conversely, more cautious economists warn that initiating an easing cycle prematurely carries inherent structural hazards. Persistent geopolitical instability across key international supply corridors poses ongoing supply-side risks to wholesale commodity prices. If unexpected supply shocks coincide with a resurgence in consumer demand spurred by looser monetary conditions, central bankers could find themselves confronting renewed inflationary spikes. Some market participants also worry that reducing borrowing costs prematurely could re-inflate asset bubbles, particularly within metropolitan real estate markets where housing shortages persist irrespective of prevailing monetary trends.
The banking sector itself faces a complex, dual-faceted adjustment period. While lower interest rates traditionally depress net interest margins by constricting the spread between deposit costs and loan returns, commercial lenders may see significant counterbalancing benefits. A reduction in systemic financing costs is expected to stem the flow of non-performing loans, reduce default provisions, and stimulate renewed underwriting volume across mortgage, commercial real estate, and syndicated corporate lending divisions.
International observers have underscored the broader cross-border repercussions of the central bank's policy path. Central banks globally are currently traversing divergent economic corridors, with some monetary authorities still contending with persistent price stickiness while others face outright disinflationary pressures. By loosening its regulatory stance, the central bank has aligned itself with peer institutions embracing gradual normalization, potentially establishing a coordinated monetary framework that could recalibrate capital allocations throughout emerging and developed markets alike.
During the subsequent post-meeting press conference, the central bank governor emphasized that the policy trajectory remains firmly data-dependent and should not be construed as a pre-programmed sprint toward an ultra-loose fiscal climate. Addressing assembled financial journalists, the governor stressed that every upcoming policy convening would evaluate emerging macroeconomic signals independently, weighing gross domestic product revisions, wage formation data, and labor force participation figures before determining further rate interventions.
The governor reiterated that the central bank maintains an asymmetric vigilance; while supportive of sustainable economic expansion, the institution remains fully prepared to pause its cutting cycle or even resume monetary tightening should persistent underlying inflationary pressures re-emerge unexpectedly. This carefully calibrated rhetoric was intentionally formulated to temper excessive market exuberance and prevent traders from pricing in an overly aggressive series of subsequent cuts throughout the remainder of the calendar year.
For mid-sized and small enterprise operators, the structural easing cycle arrives at a critical juncture. Throughout the sustained period of restrictive credit, smaller businesses struggled disproportionately with refinancing debt maturities and securing the working capital necessary to navigate supply chain fluctuations and inventory holding costs. Industry federations noted that the minor reduction, coupled with the psychological signal that interest rates have decisively crested, could substantially enhance small-business confidence, stabilizing localized hiring and commercial leasing activity.
As the initial market volatility gives way to a deeper technical assessment of the central bank's projections, economists will closely monitor the forthcoming releases of employment statistics and consumer sentiment surveys to evaluate the actual transmission velocity of the rate reduction into the broader economy. Historically, monetary policy measures operate with long and variable lags, often requiring several quarters before their full impact materializes across productive enterprise and consumer spending patterns.